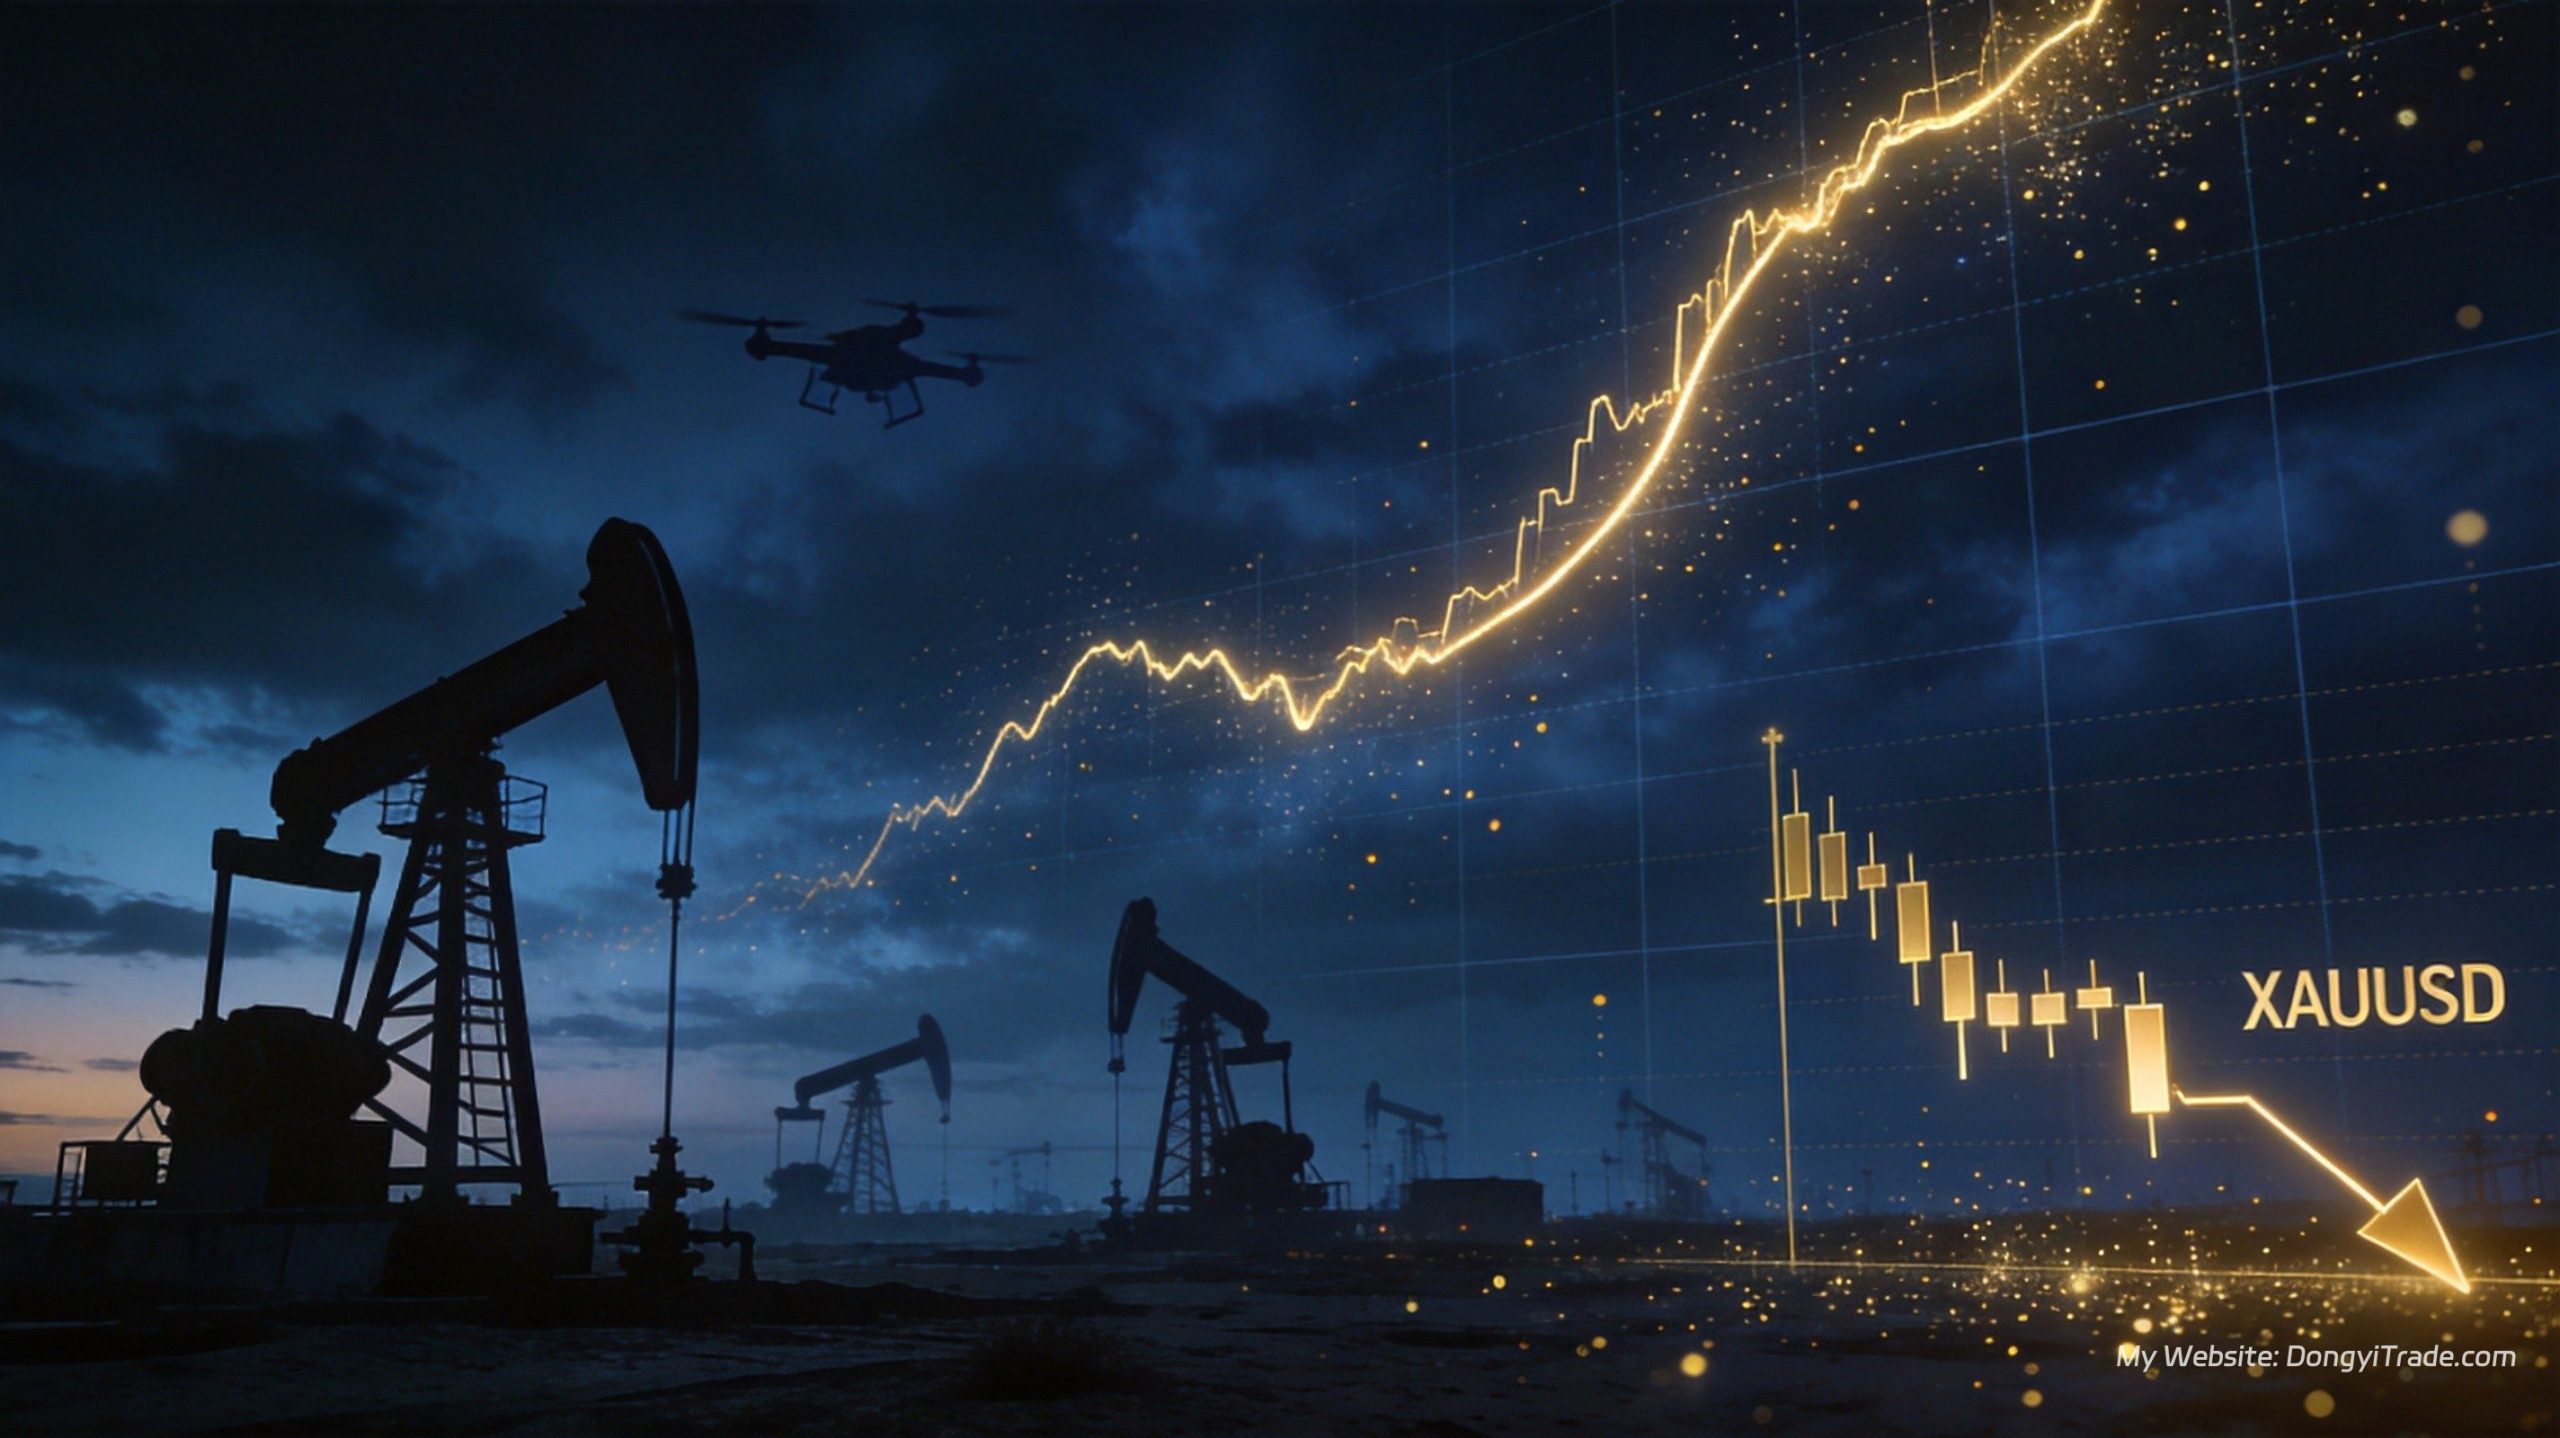
During Thursday’s (October 22) Asian session, spot gold softened toward $4,125/oz, surrendering nearly all of Wednesday’s rebound. By textbook logic, the past 24 hours should have sent bullion soaring — Houthi drones struck a Saudi Aramco oil field killing two, a separate attack on Dammam airport left one dead and eight wounded, the US State Department ordered non-emergency personnel and their families out of Saudi Arabia, and the Pentagon dispatched a third carrier strike group to the region. A triple escalation in geopolitical risk, and gold barely blinked. “Buy gold on conflict” — one of the oldest trading heuristics — is systematically failing in this cycle.
1. Why the Safe-Haven Bid Is Failing: The Chain Has Been Rerouted
In the classical framework, geopolitical conflict feeds directly into safe-haven demand and higher gold prices. The 2026 market structure has inserted an intermediate station into that line:
- Conflict lifts oil. Brent crude holds above $110/bbl; tanker attacks near the Strait of Hormuz and falling US crude inventories have drained more than 500 million barrels from global stocks since February. Strikes on Saudi oil infrastructure threaten supply directly — the path of least resistance for crude is higher.
- Oil entrenches inflation. Energy is the core driver of this cycle’s sticky inflation, with US price growth persistently above the 2% target. Even a Bank of England policymaker said this week that the inflation risk from the energy shock has exceeded expectations and rates should rise further.
- Inflation hardens hike expectations. CME FedWatch still prices roughly a 90% probability of a December hike — the same ceiling we mapped in yesterday’s ‘near-dove, far-hawk’ rate-pricing framework. On the Saudi headlines, the 2-year Treasury yield actually jumped to a one-week high.
The chain now reads: conflict → higher oil → stickier inflation → entrenched hike expectations → higher real yields → pressure on gold. The safe-haven premium is being intercepted by the rates channel halfway through. The data is unambiguous: since the US-Iran conflict erupted in late February, gold has fallen roughly 20%, sliding from the January 28 all-time high of $5,589 to the $4,100 area. The bigger the geopolitical shock, the weaker gold has been — direct evidence that the transmission chain has been rewired.
2. Where Did the Haven Flows Go? Treasuries Are Winning the Musical Chairs
Haven demand has not vanished — it has changed address. The 10-year Treasury yield fell 14.6bp last week, its largest weekly drop in eight months, evidence that safety-seeking capital is flooding into US government bonds: a 5%+ coupon plus potential capital gains if rates peak, against zero yield on gold. The positioning data agrees: SPDR Gold Shares, the largest gold ETF, shed another 2.56 tonnes on Wednesday to 1,057.62 tonnes. Speculative money keeps leaving; only central banks and the allocator bid we tracked in the ETF flow divergence remain underneath the market.
Wednesday’s rebound — from a near one-week low of $4,104.85 back to $4,141.10 — was fundamentally a rates story: the 10-year yield slipped for a second session to 5.111%, temporarily lowering the opportunity cost of holding bullion. The moment the Middle East headlines hit on Thursday and the 2-year yield popped, the rally was snuffed out. This “short-lived FX channel, dominant rates channel” signature matches our DXY-XAUUSD inverse-correlation breakdown exactly — with the dollar index parked at a three-week low of 101.69 and still unable to lift gold, the currency channel is clearly not setting prices.
3. Quant Corner: Pricing the ‘Failure Regime’
For systematic traders, the biggest trap in a safe-haven-failure regime is the legacy rule “geopolitical event → long gold.” Three executable adjustments:
- Rewrite the event playbook. Replace “escalation → buy” with “escalation → check oil and the 2Y yield.” A safe-haven long only has positive expectancy when the event does not trigger an oil spike, or when yields fall in sympathy. Otherwise, event moves tend to resolve as fade-the-rally traps — better used to lighten positions into strength.
- Trade the correlation matrix, not a single narrative. XAUUSD’s rolling correlation with oil has turned negative (oil up = inflation expectations up = gold down), while its inverse correlation with real yields sits near historical extremes. Re-weight toward the rates factor, and demote the geopolitical factor from “direction signal” to “volatility trigger.”
- Time the volatility cycle. In the midweek blackout-plus-data-vacuum stretch, gold’s daily ranges typically compress — range-trading the box works. Around Thursday’s jobless claims and Friday’s PMIs, volatility expands; widen stops dynamically with ATR or expect to be swept by routine noise.
Execution costs are decisive in headline-dense weeks. On my own ECMarkets ECN account, XAUUSD spreads stay reasonable even during Middle East headline pulses, and 0.01-lot micro sizing pins event-trade risk at exactly 1% of equity. In this regime, cost control is part of the strategy itself.
4. This Week’s Trading Framework
- Core range: A $4,100-$4,150 short-term battleground. $4,100 has been defended twice since October 15; $4,150 is Wednesday’s rebound high overlapping with the futures settle.
- Supports below: $4,066 (box floor), then the $4,000 handle. If oil keeps feeding hike expectations and yields push higher again, a test of $4,000 would not surprise — but chasing shorts into the allocator absorption zone offers poor risk/reward.
- Resistance above: $4,150, $4,180 and $4,200. Without a genuine cooling of December hike pricing, treat every rally as a trip toward the top of the box.
- Calendar risk: The Fed has entered its blackout ahead of the October 27-28 meeting. This week’s remaining data is light: jobless claims Thursday, S&P Global PMIs and the final Michigan sentiment print Friday. On the event side, watch the two-way hedge between Middle East escalation (US-Iran dialogue, further Houthi action) and Russia-Ukraine de-escalation signals (the mid-November trilateral talks).
In a range-bound tape, fill quality writes the equity curve — running box strategies on my ECMarkets ECN account keeps limit fills at the edges and stop execution reliable, the hardware foundation that turns “fade the range” from a slogan into a discipline.
💡 Key Takeaways
- Safe-haven failure confirmed: An oil-field strike, a US personnel evacuation and a third carrier group — a triple Middle East escalation — and gold still fell. Bullion is down roughly 20% since the conflict began in February; the “conflict = gold up” heuristic is broken.
- The chain is rewired: Conflict → $110+ oil → sticky inflation → ~90% December hike pricing → higher real yields. The rates channel is intercepting the haven premium.
- Flows have rotated: Safety capital is choosing Treasuries (biggest weekly 10Y yield drop in eight months) while SPDR holdings slid to 1,057.62 tonnes; only allocator money supports the floor.
- Systematic response: Rewrite event rules, tilt the correlation matrix toward the rates factor, and use ATR-dynamic stops — demote geopolitics from direction signal to volatility trigger.
- This week’s map: $4,100-$4,150 box, light positioning into the blackout and data vacuum, and let PCE plus the FOMC statement pick the direction.
About the Author: Dongyi, professional quantitative trader focused on XAUUSD gold trading strategies, running DongyiTrade (dongyitrade.com), sharing quantitative trading strategies and in-depth market analysis.
Contact: WeChat: DongyiTrade | Telegram: @DongyiTrade